Income Tax Benefits on an Under Construction Home 2027
Income tax benefits on an under-construction home at Prestige Park Ridge are claimed mainly under the old tax regime. A buyer can claim up to Rs 2 Lakhs on home loan interest under Section 24(b) and up to Rs 1.5 lakh on principal under Section 80C. The new tax regime drops these for a self-occupied home, so the choice of regime matters. This guide covers the sections, the pre-possession rule, joint owners and a worked example.
Deduction on Interest and Principal
Two core sections drive the benefit. The table below sets out the limits for the assessment year 2026-27. These are from the Income Tax Act and were unchanged in the Union Budget 2026-27.
| Section | What It Covers | Annual Limit |
|---|---|---|
| Section 24(b) | Home loan interest, self-occupied | Rs 2 lakh |
| Section 80C | Principal repayment | Rs 1.5 lakh |
| Section 80EEA | Extra interest, closed window | Rs 1.5 lakh |
Section 80EEA applied only to loans sanctioned between April 2019 and March 2022. A buyer taking a fresh loan today cannot claim it. For most new buyers, Sections 24(b) and 80C are the two that apply.
How Pre-Possession Interest Is Claimed
An under-construction home has a special interest rule. The interest paid during construction cannot be claimed in the year it is paid. Instead, that interest is added up until the home is ready.
From the year possession begins, the total is claimed in five equal annual instalments. Each instalment stays within the Rs 2 lakh cap for a self-occupied home. Principal repaid during construction does not get this instalment treatment.
Old Regime Against New Regime
The regime chosen decides whether these benefits apply at all. The old regime allows Section 24(b), Section 80C and the pre-possession interest rule. Many home buyers stay on it for this reason.
The new regime offers lower slab rates but drops these deductions for a self-occupied home. The only home loan benefit that survives under the new regime is interest set off against rental income from a let-out property. Compare the tax saved under each regime before choosing.
Benefits for Joint Owners and Co-Borrowers
A joint home loan can widen the benefit. Each co-owner who is also a co-borrower claims the deductions separately. So two eligible owners can each claim up to Rs 2 lakh interest and Rs 1.5 lakh principal.
The claim is based on each person's ownership and repayment share. Both owners must be on the loan and on the title to claim.
If Possession Is Delayed and a Worked Example
Possession timing affects the interest cap. The full Rs 2 lakh interest benefit for a self-occupied home applies when construction completes within the limit set in the Act. A long delay beyond that limit can reduce the cap, so the agreed possession date matters.
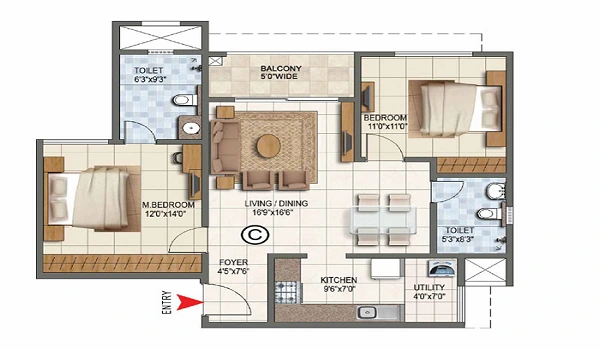
Take a salaried buyer of a 2 BHK at Rs 1.35 crore, with a Rs 1.08 crore loan at 8 percent. Under the old regime, the buyer claims Rs 2 lakh interest under Section 24(b) and Rs 1.5 lakh principal under Section 80C once possession begins. Tax rules are personal and change with each Budget, so a tax professional should be consulted for the exact figures in any case.
Benefits on a Let-Out Property
The rules change if the home is let out. There is no Rs 2 lakh cap on interest for a let-out property under the old regime. The full interest can be set against the rental income.
A resulting loss from house property can be set off up to Rs 2 Lakhs against other income each year. Any balance carries forward for up to eight years. This is the one home loan benefit that also survives under the new regime.
Rent received is taxable under income from house property. A standard deduction of 30 percent applies on the net annual value. The rent agreement and receipts should be kept, as the tax office may ask for them.
Frequently Asked Questions
Yes, but the interest paid during construction is claimed only from the year of possession. It is then spread over five equal annual instalments within the Rs 2 lakh cap.
A buyer can claim up to Rs 2 lakh a year on home loan interest for a self-occupied home. This limit applies under the old tax regime.
No, not for a self-occupied home. The new regime drops Section 24(b) and Section 80C. Only interest against a let-out property survives.
Yes. Each co-owner who is also a co-borrower claims up to Rs 2 lakh interest and Rs 1.5 lakh principal separately, by their share.
Section 80C allows up to Rs 1.5 lakh a year on principal repayment. This falls within the overall Section 80C cap that covers other savings too.
The interest paid still accrues and is claimed from possession in five instalments. A long delay beyond the limit in the Act can reduce the Rs 2 lakh cap, so the timeline matters. The loan statements and the possession letter should be kept for the claim. A tax professional can confirm the exact figures, which keeps the deduction clean at filing.