
Prestige Park Ridge EMI Calculator
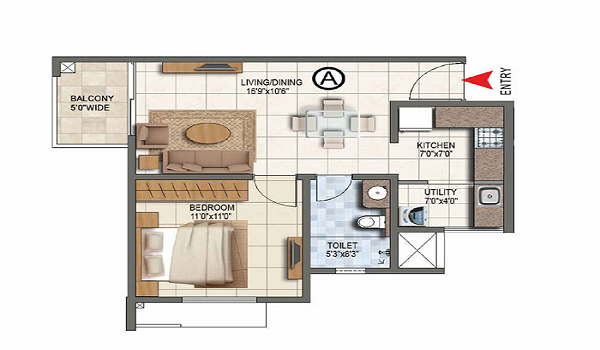
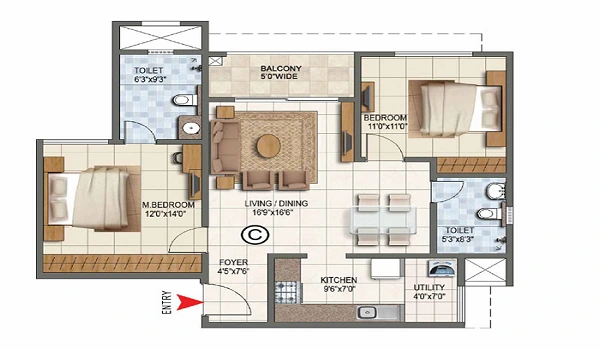
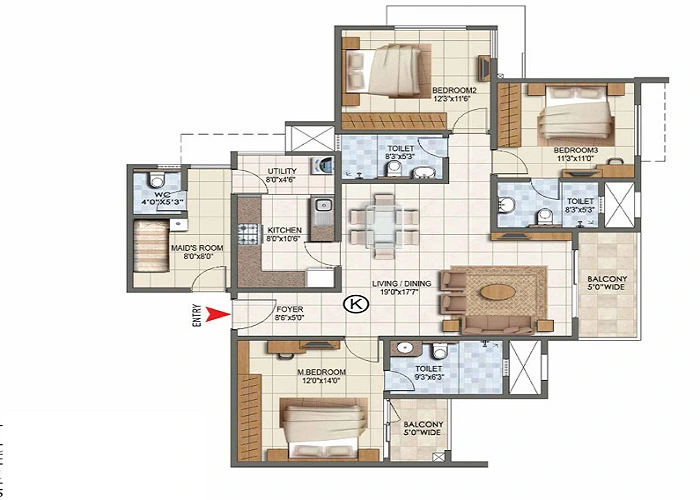
An EMI calculator helps you work out your monthly home loan payment before you pick a unit at Prestige Park Ridge on Bannerghatta Road. You enter the loan amount, the interest rate, and the loan tenure. The tool then gives you an instant monthly figure. You might be eyeing a compact 1 BHK near 700 sq ft. Or you might want a larger 3 BHK past 1,500 sq ft. Either way, running this check early helps you set a realistic budget. This matters well before you sign any agreement.
Project Stage and Pricing at a Glance
Prestige Park Ridge is currently in its pre-launch phase, with Expression of Interest opening on 3 October 2026 and possession planned for mid-2031. The project's RERA number is still under process. It has not been issued yet. Pricing during this pre-launch window starts near Rs 85 Lakhs for a 1 BHK. It moves past Rs 1.8 Crore for the larger 3 BHK homes. This range is what most buyers plug into an EMI calculator first. They narrow it down to a specific unit later.
What Does a Home Loan EMI Calculator Actually Do
A home loan EMI calculator is a free tool that works out the fixed sum you owe your bank each month. EMI stands for Equated Monthly Instalment. Each payment covers a part of your loan principal. It also covers the interest charged on it, until the loan is fully repaid. The full calculation rests on three simple inputs.
- Loan Principal: The actual amount you borrow once your down payment is set aside.
- Interest Rate: The yearly percentage your chosen lender charges on the loan.
- Loan Tenure: The number of years you choose to repay the full amount.
How This Plays Out for a Prestige Park Ridge Home Loan
Once you enter these three numbers, the tool runs them through a set formula. It shows your monthly payment at once. Moving the tenure slider changes the result in a clear way. A longer tenure brings your monthly EMI down. But it also raises the total interest you pay in the end. Take a loan of Rs 1.08 Crore at 8.5 percent interest over 20 years. That works out to about Rs 93,725 a month. Stretch it to 25 years, and the figure drops close to Rs 86,965. Your total interest bill still climbs higher over those extra five years. The monthly load, though, feels much lighter.
Estimated Monthly EMI Across Loan Brackets
The table below shows how your EMI changes as the loan amount goes up, based on an 8.5 percent interest rate over a standard 20 year term. Treat the income column as a rough guide. Lending rules vary from bank to bank.
| Loan Amount | Estimated Monthly EMI | Recommended Monthly Income |
|---|---|---|
| Rs 60 Lakhs | Rs 52,069 | Rs 1,30,000 |
| Rs 70 Lakhs | Rs 60,748 | Rs 1,52,000 |
| Rs 90 Lakhs | Rs 78,104 | Rs 1,95,000 |
| Rs 1.10 Cr | Rs 95,461 | Rs 2,39,000 |
| Rs 1.30 Cr | Rs 1,12,817 | Rs 2,82,000 |
| Rs 1.44 Cr | Rs 1,24,967 | Rs 3,12,000 |
| Rs 1.60 Cr | Rs 1,38,852 | Rs 3,47,000 |
Why You Should Check the EMI Before You Book a Unit
Running these numbers early keeps your budget steady once possession dates and other costs start piling up.
- Stress Free Budget Planning: Knowing your EMI early shows how much income the loan will use. This leaves room for daily costs and savings.
- Comparing Down Payment Options: A bigger upfront amount brings your monthly bill down. It also cuts your total loan load.
- Balancing the Loan Tenure: A short tenure raises your EMI but saves money on interest. A long tenure eases the load but costs more in the end.
- Knowing Your True Budget Limit: A quick check keeps you away from homes outside your budget.
A Sample Cost Breakdown for a 3 BHK at Prestige Park Ridge
Working out your real mortgage cost means separating your own savings from the amount you plan to borrow from the bank.
- Total Agreement Value: Rs 1.8 Crore
- Upfront Down Payment (20 percent): Rs 36 Lakhs
- Net Home Loan Principal: Rs 1.44 Crore
- Assumed Interest Rate: 8.5 percent per year
- Selected Loan Tenure: 20 years
- Resulting Monthly EMI: around Rs 1,24,967
What Can Change Your Final Bank Approved EMI
Your bank's final offer can differ a little from any online estimate. Real approvals also depend on your credit history and the lender's own rules.
- Your CIBIL Score: A score above 750 usually gets you a lower rate from most banks.
- Interest Rate Type: A floating rate moves with the market over time. A fixed rate stays the same for the full tenure.
- Verified Monthly Income: Banks check your salary slips or business income. This confirms you can manage the EMI with ease.
- Existing Debts: Running car loans or heavy credit card bills can reduce your loan offer.
Simple Ways to Bring Your Monthly EMI Down
A few practical steps can ease the monthly load if your estimated EMI feels a little too high for comfort.
- Make a larger down payment so you borrow less from the bank overall.
- Use annual bonuses or investment returns to make part payments against the principal.
- Compare offers across a few banks before locking in your final interest rate.
Extra Costs Beyond Your Monthly Loan Payment
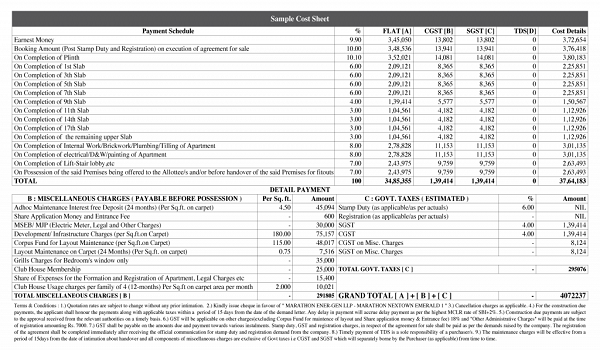
Buying a home at Prestige Park Ridge also brings a few one time costs that sit outside your regular EMI. It helps to set this cash aside separately from the start.
- Stamp Duty and Registration: A government charge to register the property in your name.
- Bank Processing Fees: A one time charge to verify your papers and approve the loan.
- Maintenance Advance: An upfront deposit that covers early upkeep of shared spaces and amenities.
FAQs
It helps you check your monthly home loan payment before you finish a booking. The result is based on the loan amount, interest rate, and tenure you choose.
At 8.5 percent for 20 years, this loan comes to roughly Rs 93,725 a month. Your exact figure depends on the rate your bank offers.
The project's RERA registration is under process as of September 2026. EOI opens on 3 October 2026, with possession planned for mid-2031.
A longer tenure lowers your monthly EMI but raises your total interest cost. A balanced tenure that keeps both figures reasonable usually works best.
A larger down payment helps, along with a strong CIBIL score above 750. Part payments toward the principal also bring your EMI down over time.
No, the calculator only estimates your loan repayment. Stamp duty, registration, processing fees, and maintenance deposits sit outside the EMI. Budget for these on your own.